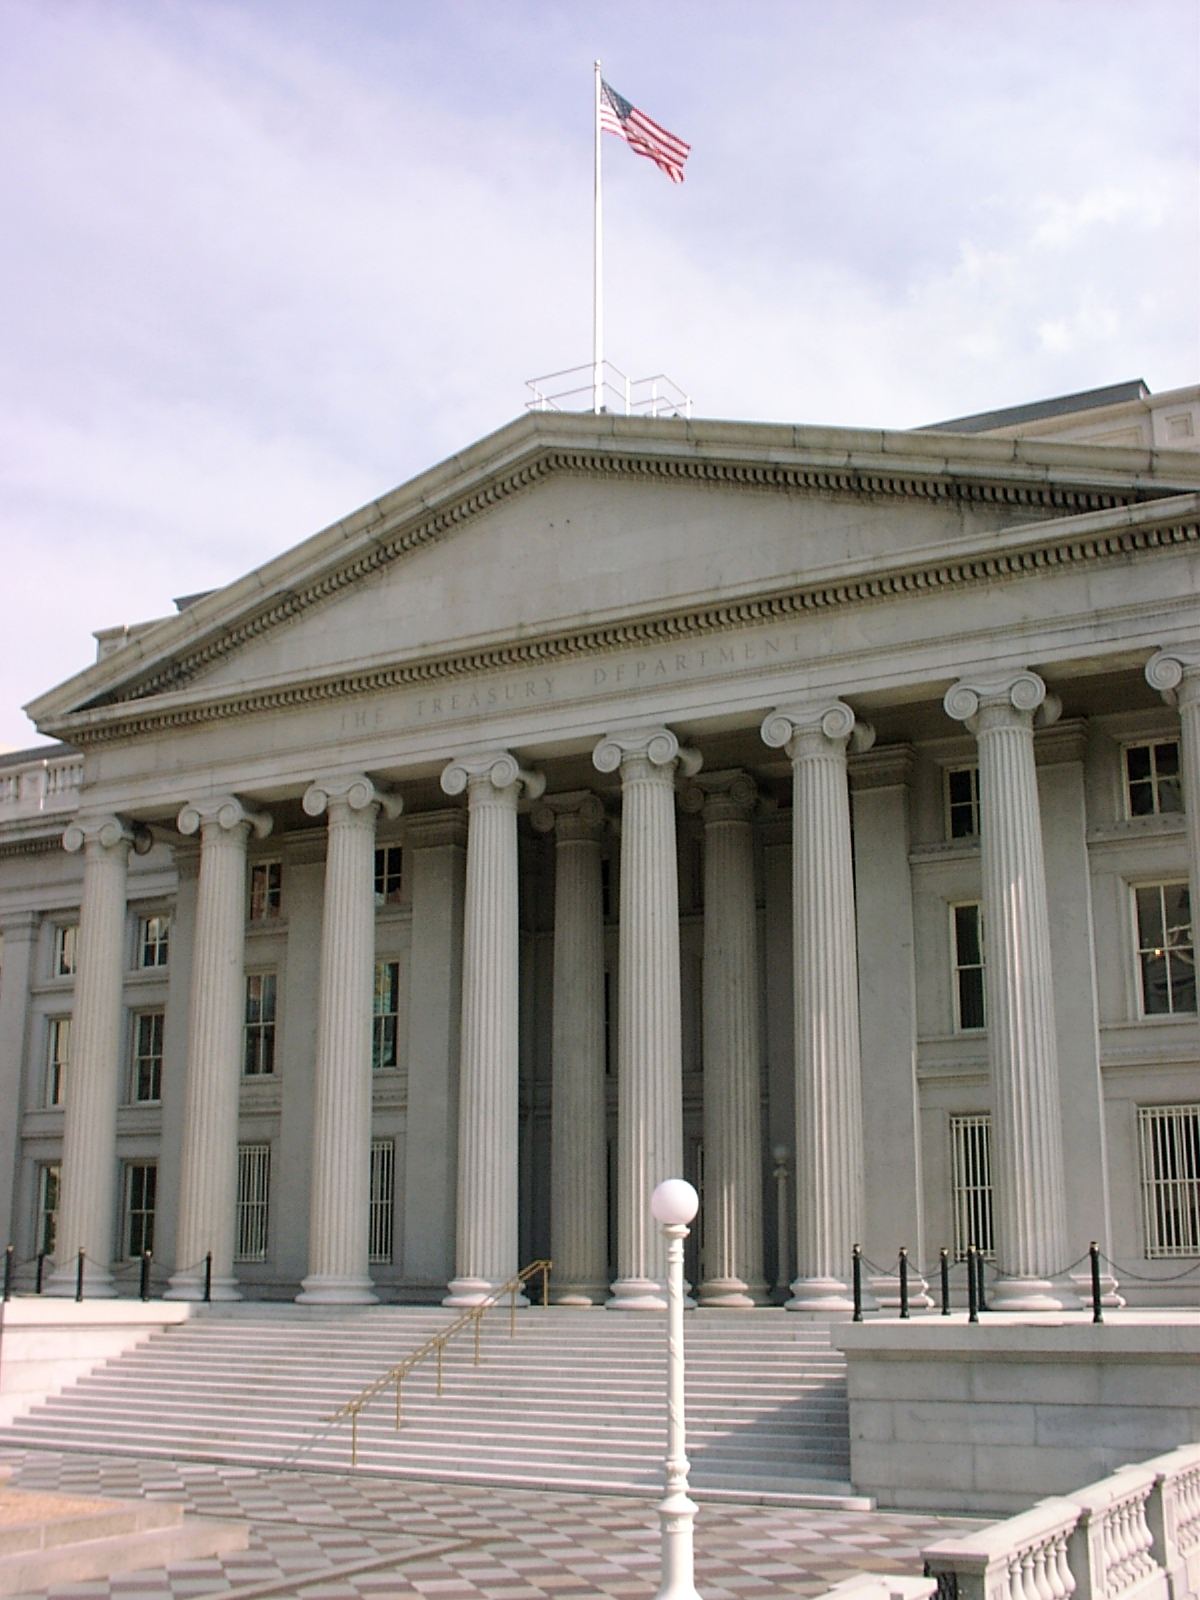

Government bonds, once the preserve of banks and large funds, are being issued in tokenised form, opening the market to a wider group of investors. Tokenisation turns a bond into a digital record on a blockchain, which can be divided into much smaller pieces than a traditional bond and traded more easily between buyers and sellers. Several governments have now sold tokenised bonds in public sales, and the buyers have included pension funds, asset managers and, in smaller amounts, ordinary investors using regulated platforms. Supporters say the technology makes settlement faster, since ownership changes as soon as the trade is agreed rather than days later, and it gives issuers a clearer view of who holds their debt. For governments, the sales are also a way to test whether digital markets can make borrowing cheaper and more transparent over time. The first sales attracted strong interest, and several more governments are now preparing their own tokenised issues.
What the Evidence Shows
The market is still small, and several obstacles remain before tokenised bonds become routine. Trading volumes are thin, so buying or selling a large amount can still move the price, and the rules differ from one country to another, which limits cross-border trading. Custody is another question, since investors need a safe place to hold the digital tokens, and many traditional custodians are only now building the systems to do so. Regulators are working on common standards, and banks are building platforms that let clients hold tokenised and traditional bonds side by side. Market watchers say the real test will come when a tokenised bond is issued in a large size and trades actively for months. If that happens, tokenisation could quietly reshape one of the oldest and largest markets in finance. Reporting and analysis from sources such as Bank for International Settlements track the same developments, and specialists following tokenised government bonds say the direction is now consistent across independent lines of evidence.
The Wider Context
The wider context is a sector being absorbed, piece by piece, into the regulated financial mainstream. Work on tokenised government bonds now happens under licensing regimes, audit expectations and consumer-protection rules that would have been unrecognisable a few years ago. Long-standing participants are divided between relief at the legitimacy and regret for the experiment’s wilder freedoms.
What Happens Next
What happens next for tokenised government bonds will be shaped by the interaction of regulation, market appetite and the sector’s own capacity for self-inflicted wounds. The infrastructure is more professional than it was, the rules are clearer, and the remaining question is whether growth can stay boring. Participants with the longest memories say boring would be the real milestone. You can follow related developments in our coverage of crypto.
There is a practical lesson in all of this for readers deciding what to do today. Start with the verified facts, be wary of anyone promising certainty, and prefer reversible steps while the evidence is still developing. Circumstances differ by country, income and personal situation, so general guidance should always be weighed against your own context before you act on it in any significant or lasting way.